Manchester City’s rule-breaking may go beyond football. The independent Commission found that the club inflated its income, concealed expenses and paid a key individual through a sham consultancy. Leaked documents identify him as City’s manager, Roberto Mancini, with payments routed to his company, Sparkleglow Holdings Ltd. We believe the evidence points to £12m in unpaid UK tax. The consequences could include a much larger tax bill and a criminal investigation.
This report is subject to four important caveats.
First, our analysis assumes that the Commission’s findings of fact are correct. City maintains its innocence and says it will appeal, alleging material errors of law, principle and fact (but not identifying any of them).
Second, we have only the heavily redacted, 40-page core decision. The detailed appendices remain unpublished. They are likely substantial: the parties’ document index alone ran to 750 pages.
Third, we rely on documents obtained by Der Spiegel as part of the Football Leaks investigation, and on the original 2018 reporting by Der Spiegel and L’Espresso, also covered by The Guardian. We have reviewed the underlying materials ourselves and assume the documents are authentic; to our knowledge, this has never been questioned.1
Four, we make no claims that any named individuals committed tax evasion or other criminal offences; the facts suggest that they may have done, but this will depend on their state of mind at the time.
This report is therefore a preliminary assessment based on the evidence currently available. We conclude:
- Roberto Mancini received large payments under a consultancy contract with Al Jazira Sports and Cultural Club.
- On the basis of the Commission’s findings and leaked documents, the contract was a sham, and in reality represented remuneration for Mr Mancini’s employment with Manchester City.
- Manchester City should therefore have applied UK PAYE income tax and National Insurance in the usual way – but the evidence suggests it didn’t. It’s likely around £12m of tax went unpaid.
- We don’t know whether HMRC has commenced an investigation into these arrangements and, if it has, whether it has been resolved – but there’s no sign of any settlement payments in Manchester City’s accounts.
- The highly irregular nature of the arrangement, and the Commission’s findings of sham and intentional concealment, suggest to us that there should be a criminal investigation into whether tax evasion offences were committed.
- The Commission’s finding that Manchester City knowingly filed false accounts suggest that Companies Act criminal offences may have been committed.
The decision
The independent Commission’s published decision describes two separate ways in which Manchester City manipulated its finances. The point was to circumvent, and indeed break, the rules limiting how much clubs can spend relative to their income.
First, Manchester City inflated its income. The club recorded funding from its owner, Abu Dhabi United Group (ADUG), as sponsorship revenue, which boosted City’s reported income by more than £830m across the 2009/10 to 2017/18 seasons.
Second, it hid its expenses. The club’s accounts omitted costs which were really City’s, but which ADUG paid. These omitted payments understated expenses by £8.866m, £7.4m and £500,000 for three individuals. There was a complex related arrangement involving players’ image rights and an entity called Fordham.
As the decision puts it:
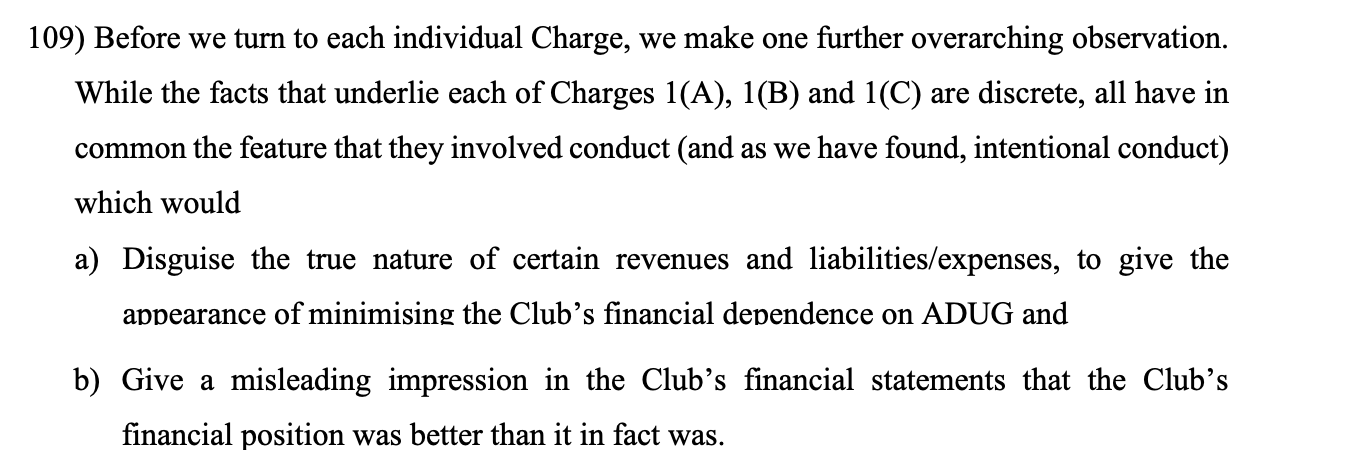
This report focuses mainly on the payments to the first of those individuals. The other hidden payments may raise similar issues, but we have less information about them. We also talk about the general criminal law implications of filing false accounts.
The wider inflation of income probably doesn’t have adverse tax consequences for City, although not enough information is available at the moment to say that with any confidence. Conversely, whilst it’s sometimes suggested the deception means that City overpaid corporation tax2 or VAT3
The arrangement with Roberto Mancini
The decision describes an arrangement under which remuneration for services contracted to be provided to City by an individual was instead recorded in a consultancy agreement between the individual and another party, funded by £8.866m from ADUG. The description is heavily redacted:
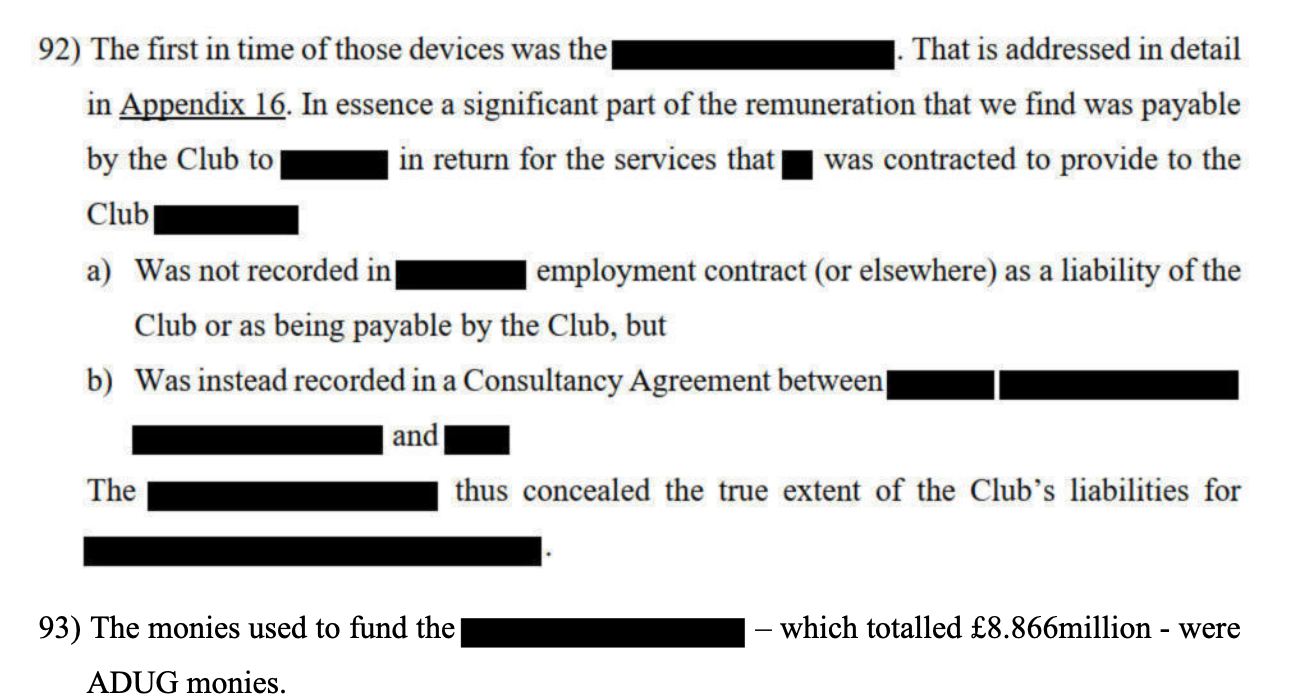
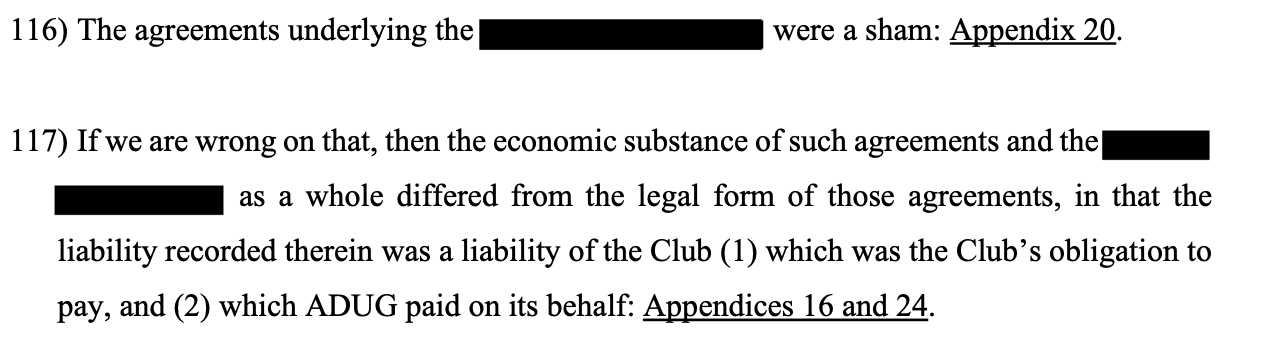
The decision then says that the contractual agreements were a sham but that, if the decision is wrong on that, City was the entity obliged to make the payments under the agreements, and ADUG made them on City’s behalf. The terms should have been included in the individual’s contract with City.
The name of the individual (and even their gender) is redacted.
Previous reports have said it was Roberto Mancini (and more on those reports below). We can, however, be reasonably confident it was Mr Mancini without needing to rely on these reports. Take a look at the description in the decision of the rules that were breached:
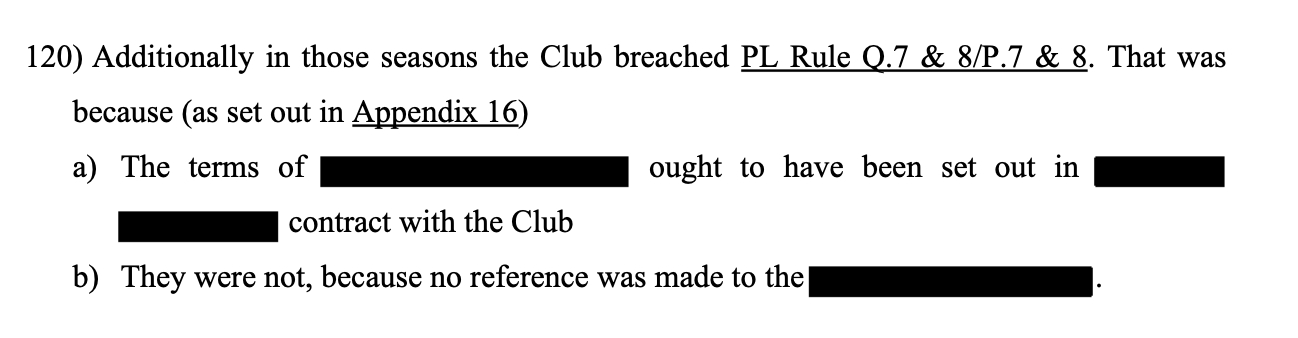
PL Rules Q.7/P.7 and Q.8/P.8 relate to manager contracts of employment, so this arrangement definitely related to a manager. There were four managers during the period in question (2009/10 to 2017/18): Pep Guardiola, Mark Hughes, Roberto Mancini and Manuel Pellegrini (plus Brian Kidd, caretaker for the last two games of 2012/13). But the decision says in paragraph 118 that the arrangement related to four seasons. Only one of those managers served for four seasons in this period: Mr Mancini.
We can double-check by looking at the length of the redacted text. For example, in this paragraph:
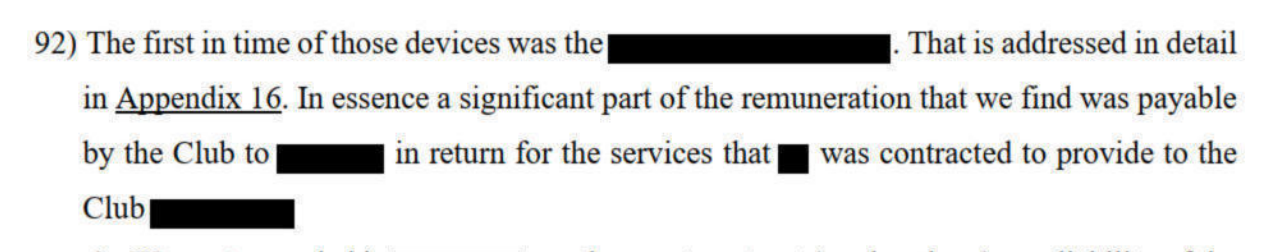
We measured the black box after “payable by the Club to” as 40.3 points wide. “Mancini” in the same font (12pt Times New Roman) would be 40.0 points wide. The names of the other managers during this period are either too small (“Hughes”, 36.7 points) or too large (“Pellegrini”, 46.7 points, and “Guardiola”, 48.0 points).4
The Commission’s findings are also consistent with the facts and chronology revealed by documents leaked in 2018, which name Mr Mancini throughout.
The chronology
The “Football Leaks” revealed a 53-page bundle5 of documents relating to Mr Mancini. Neither Mr Mancini nor Manchester City has disputed the authenticity of these documents. They are also consistent with the findings in the Commission’s decision, and, critically, the payments listed in the bundle add up to the £8,866,367 figure used in the decision.6
If we discard the possibility that the bundle is forged, we are confident that it is describing the same arrangement that is the subject of the Commission’s decision.
Here’s the initial chronology revealed from the bundle, most of which was previously reported by Der Spiegel and L’Espresso:
- 19 December 2009: Manchester City signs an agreement in principle (a “heads of agreement“) with Mr Mancini giving him a basic salary of £1,450,000 per season on a net basis, after deduction of tax. This kind of “net-of-tax” salary would be extraordinary in most of the business world, but is the norm in football: the club bears the tax.
- Also 19 December 2009: Al Jazira Sports and Cultural Club sends Mr Mancini heads of agreement for a “Consulting Agreement” (pp.5-6). Al Jazira would pay Mr Mancini’s company (unspecified) a fee of £1,750,000 per year for coaching services in Abu Dhabi, for “a minimum of [4] days per Year”. The fees “will be paid without deduction of any taxation”. Al Jazira is, like Manchester City, owned by Sheikh Mansoor.
- March 2010: The consultancy agreement is finalised (see pages 7-17). It’s signed between Al Jazira and Sparkleglow Holdings Ltd, a Mauritian company, for four days each year. The commencement date is 1 January 2010, and the fee is £1.75m a year plus a “Signing On Fee” of £62,328.77.
It’s hard to explain why Mr Mancini would receive more money from a four day consultancy contract than from his main employer. Harder still to explain the strange signing-on fee. But perhaps because the 1 January commencement date for the consultancy agreement is 13 days after Mr Mancini was appointed as manager at City, and £1,750,000 × 13/365 = £62,328.77?
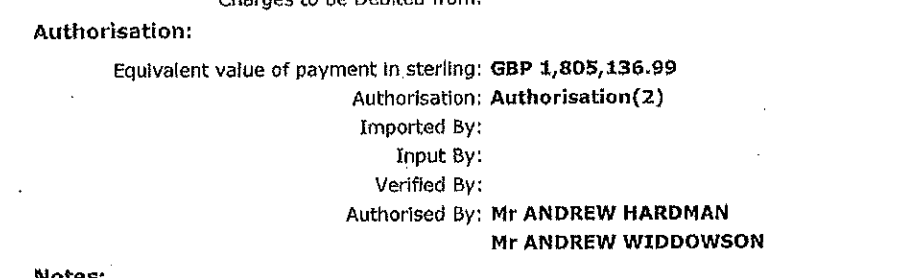
Things became clearer when, on 25 March 2011, Sparkleglow asked Al Jazira to pay the first £1,805,136.99.
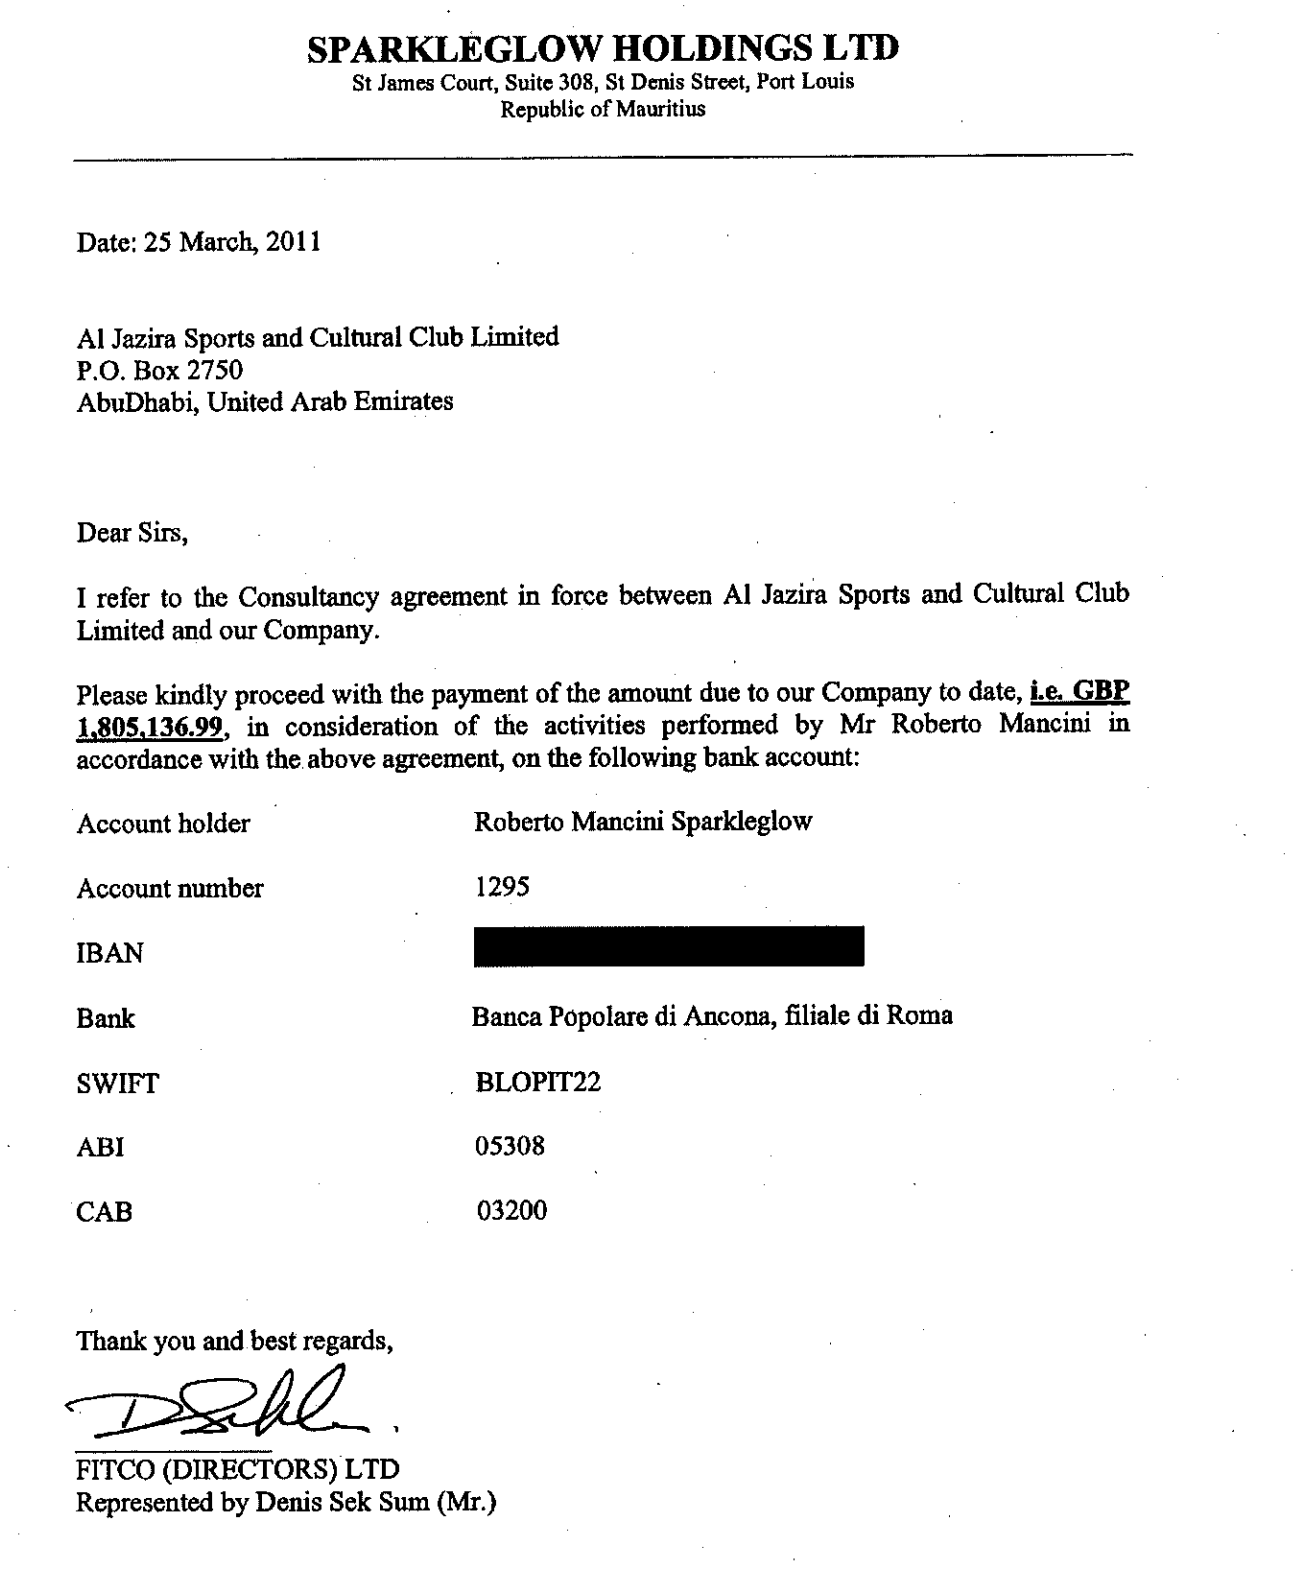
This exact amount is paid, but not by Al Jazira:
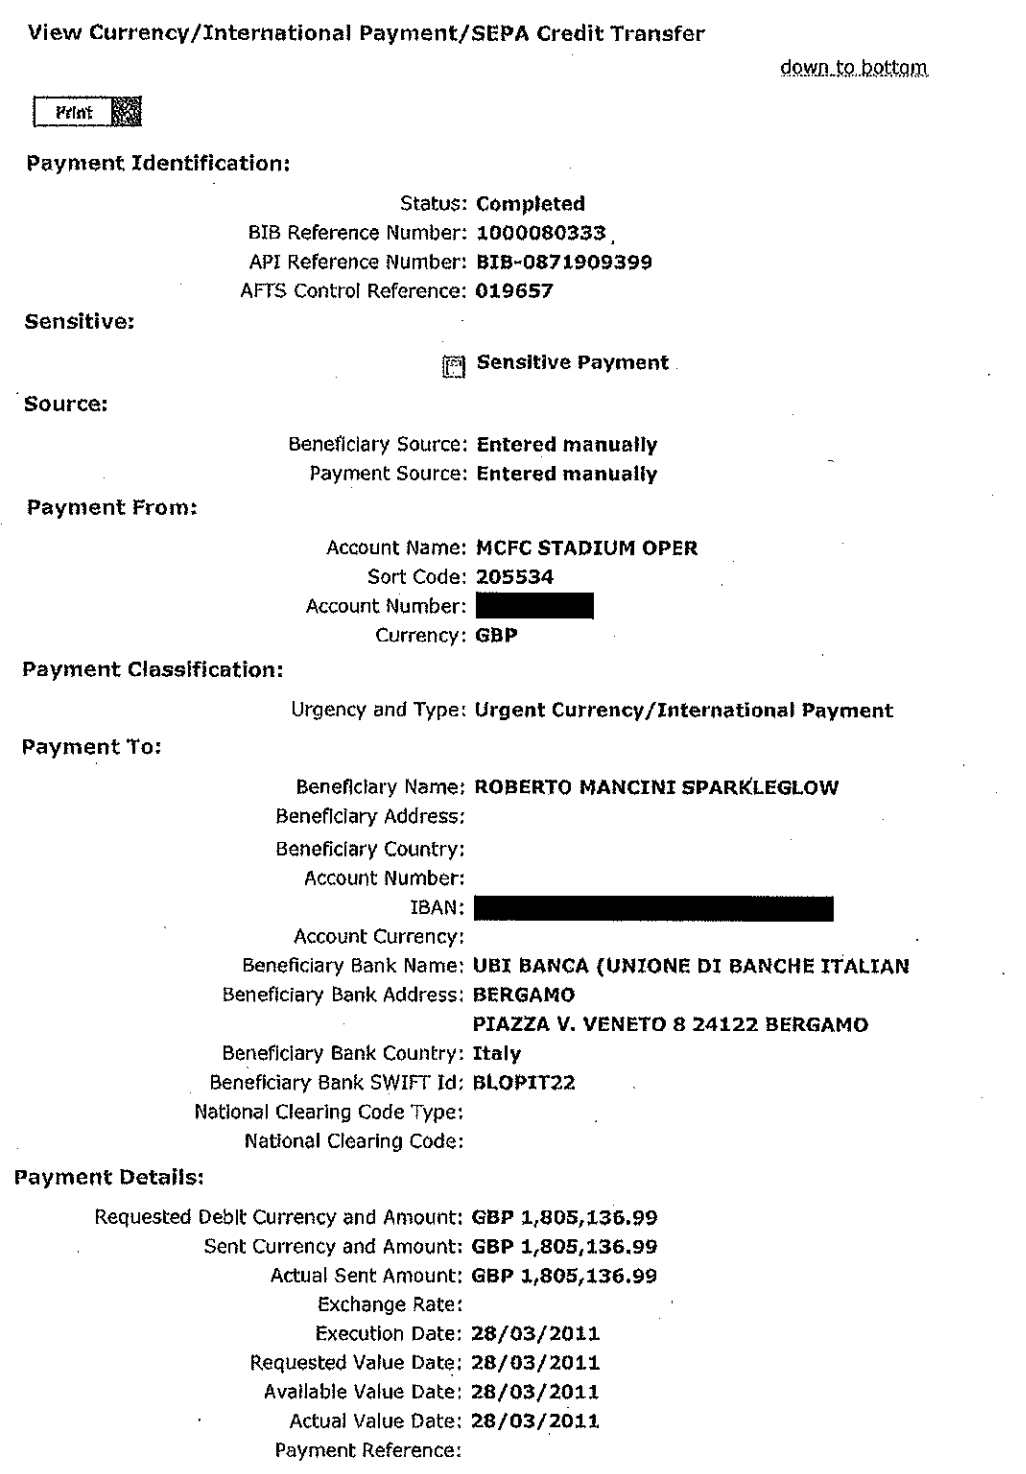
The payment was made from an account with Barclays Bank Manchester called “MCFC Stadium Oper” and authorised by the head of finance at Manchester City:7
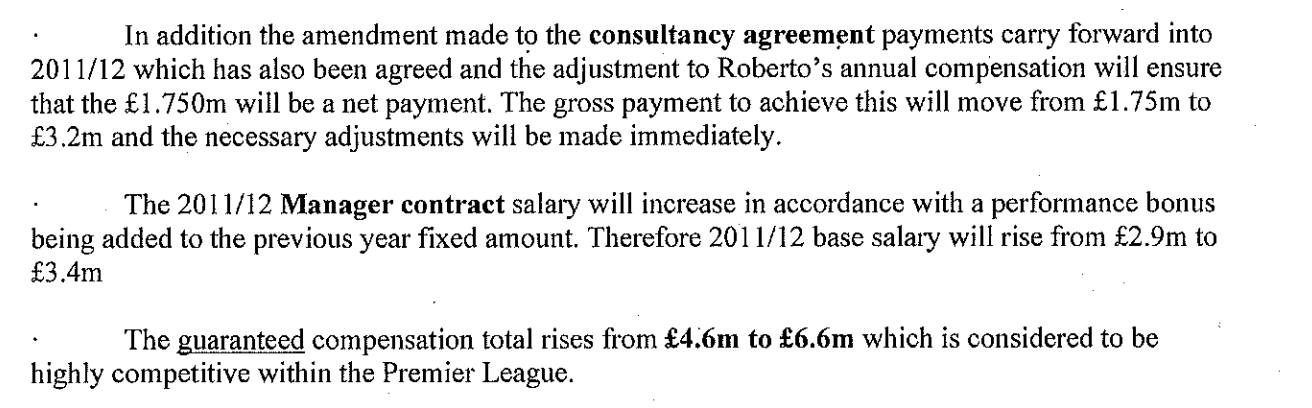
When Mr Mancini’s lawyer sought to renegotiate elements of the consultancy contract, she did not write to Al Jazira. She wrote to City’s chief executive, Garry Cook.
Manchester City, of course, was not a party to the consultancy contract. But Mr Cook nevertheless agrees to make an additional payment to cover Mr Mancini’s Italian tax, and says explicitly that this was all part of Mr Mancini’s overall compensation:
The arrangement changed in July 2011 (possibly for Italian tax reasons). The Sparkleglow consultancy agreement was terminated with effect from 31 March 2011 and replaced by a new consultancy agreement between Al Jazira and Italy International Services srl (pages 30-39), a Rome company at the address of Mr Mancini’s lawyers.
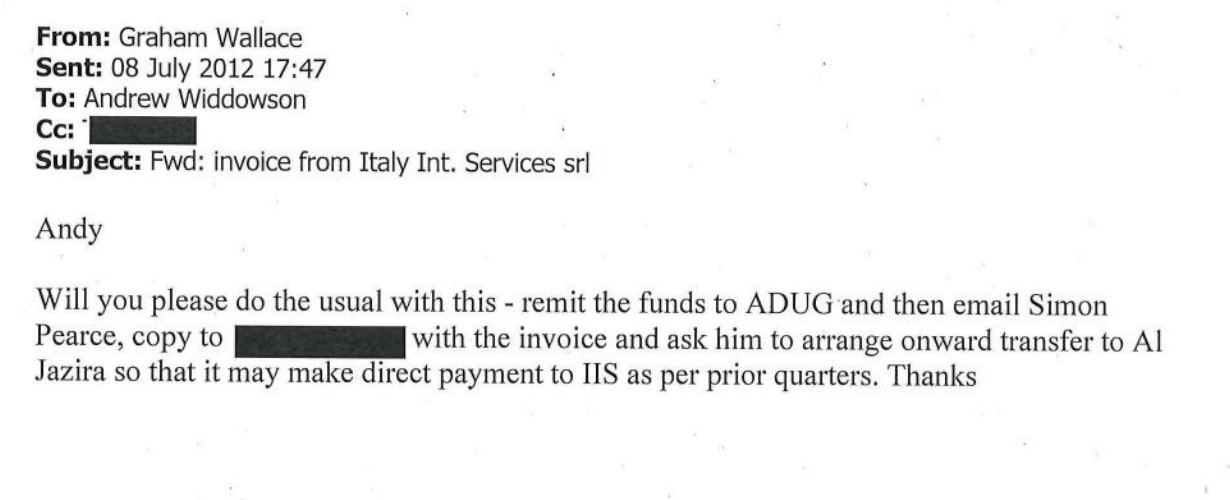
There then seems to have been some attempt to hide what was going on. When payments were made, the Italian company sent invoices to Al Jazira. Then City paid ADUG, ADUG sent the money to Al Jazira, and Al Jazira paid the Italian company.
This all became routine. Here’s City’s chief operating officer asking the head of finance to arrange the payments.
So it is not at all surprising that the Commission’s decision says this was a “sham” or, failing that, ADUG acting on behalf of Manchester City:
On the evidence of the leaked documents, this is one of the clearest cases of sham our team has seen.
Should Manchester City have paid tax on Mr Mancini’s consultancy income?
Mr Mancini was, we assume, fully taxed on his income under his main contract with Manchester City. The club will have applied PAYE to deduct income tax and employee National Insurance from his wages, and paid employer National Insurance on his gross wages.
The position for Mr Mancini’s consultancy agreement should have been the same.
You can’t magically make a salary untaxed by calling it a consultancy fee. If the payments were really for Mr Mancini’s work at Manchester City, they were employment earnings and should have been taxed accordingly.
The law looks at what a payment is for, not just what the contract calls it. Taxable “earnings” include salary, wages and “anything else that constitutes an emolument of the employment”. That’s deliberately broad. A payment can be employment income even if it comes from someone other than the employer.8
National Insurance is a separate charge. Remuneration derived from employment generally falls within the Class 1 rules, creating both employee and employer liabilities. Again, changing the label or diverting the payment through another party won’t change the result.
So it doesn’t matter who made the payment under the consultancy agreement, or which person/company received it. It was Mr Mancini’s earnings, and the club should have put it through payroll.9
There should therefore have been UK tax. Manchester City should have applied PAYE and National Insurance to its payments to Mr Mancini under the consultancy agreement in exactly the same way as under his main employment contract.10
Did Manchester City pay the tax?
It seems likely that it did not.
We can say that for several reasons.
First, we can infer it from the absence of any discussion of UK tax in the discussion of the consultancy agreement in the leaked correspondence, which is very focussed on Italian tax. By contrast, UK tax is mentioned in the context of Mr Mancini’s “normal” wages from City.
Second, and more conclusively, the correspondence talks about Italian tax being paid by Mr Mancini at 45.1%.11 There is a double tax treaty between the UK and Italy which means that, where someone is employed by a UK company and carrying on employment in the UK, the UK always has the right to tax their employment income.
So Manchester City should have been applying UK income tax and National Insurance. It’s possible Mr Mancini also had some Italian tax liability (e.g. if he was resident in Italy for some of the years in question), and in principle he could credit UK tax against that, but UK tax should have been the main consideration. The correspondence shows that it wasn’t even discussed.
The Italian tax was about £1m a year cheaper than the UK tax that should have been paid. Because Mr Mancini’s deal was “net”, this was City’s saving, not Mr Mancini’s.12
We doubt anyone at City ever made this comparison. The original arrangement, with a Mauritian company and fees paid “without any deduction or withholding whatsoever in respect of any taxation“, looks as if it was intended to result in no tax anywhere. Italian tax only appears in the documents in mid-2011, when Mr Mancini’s lawyer asked for “a compensation for the higher taxes to be paid”. So Italian tax was probably a late addition, not a choice.
And there’s another reason City may not have wanted to pay UK tax: it would have undone the pretence. PAYE only applies to an employee’s pay. Operating it would have been an admission that the consultancy fees were really Mr Mancini’s salary from City. The payments would then have had to appear in City’s accounts as staff costs, which is exactly what the arrangement was designed to avoid.
We asked Manchester City’s press office if it could confirm that PAYE and National Insurance were correctly paid:
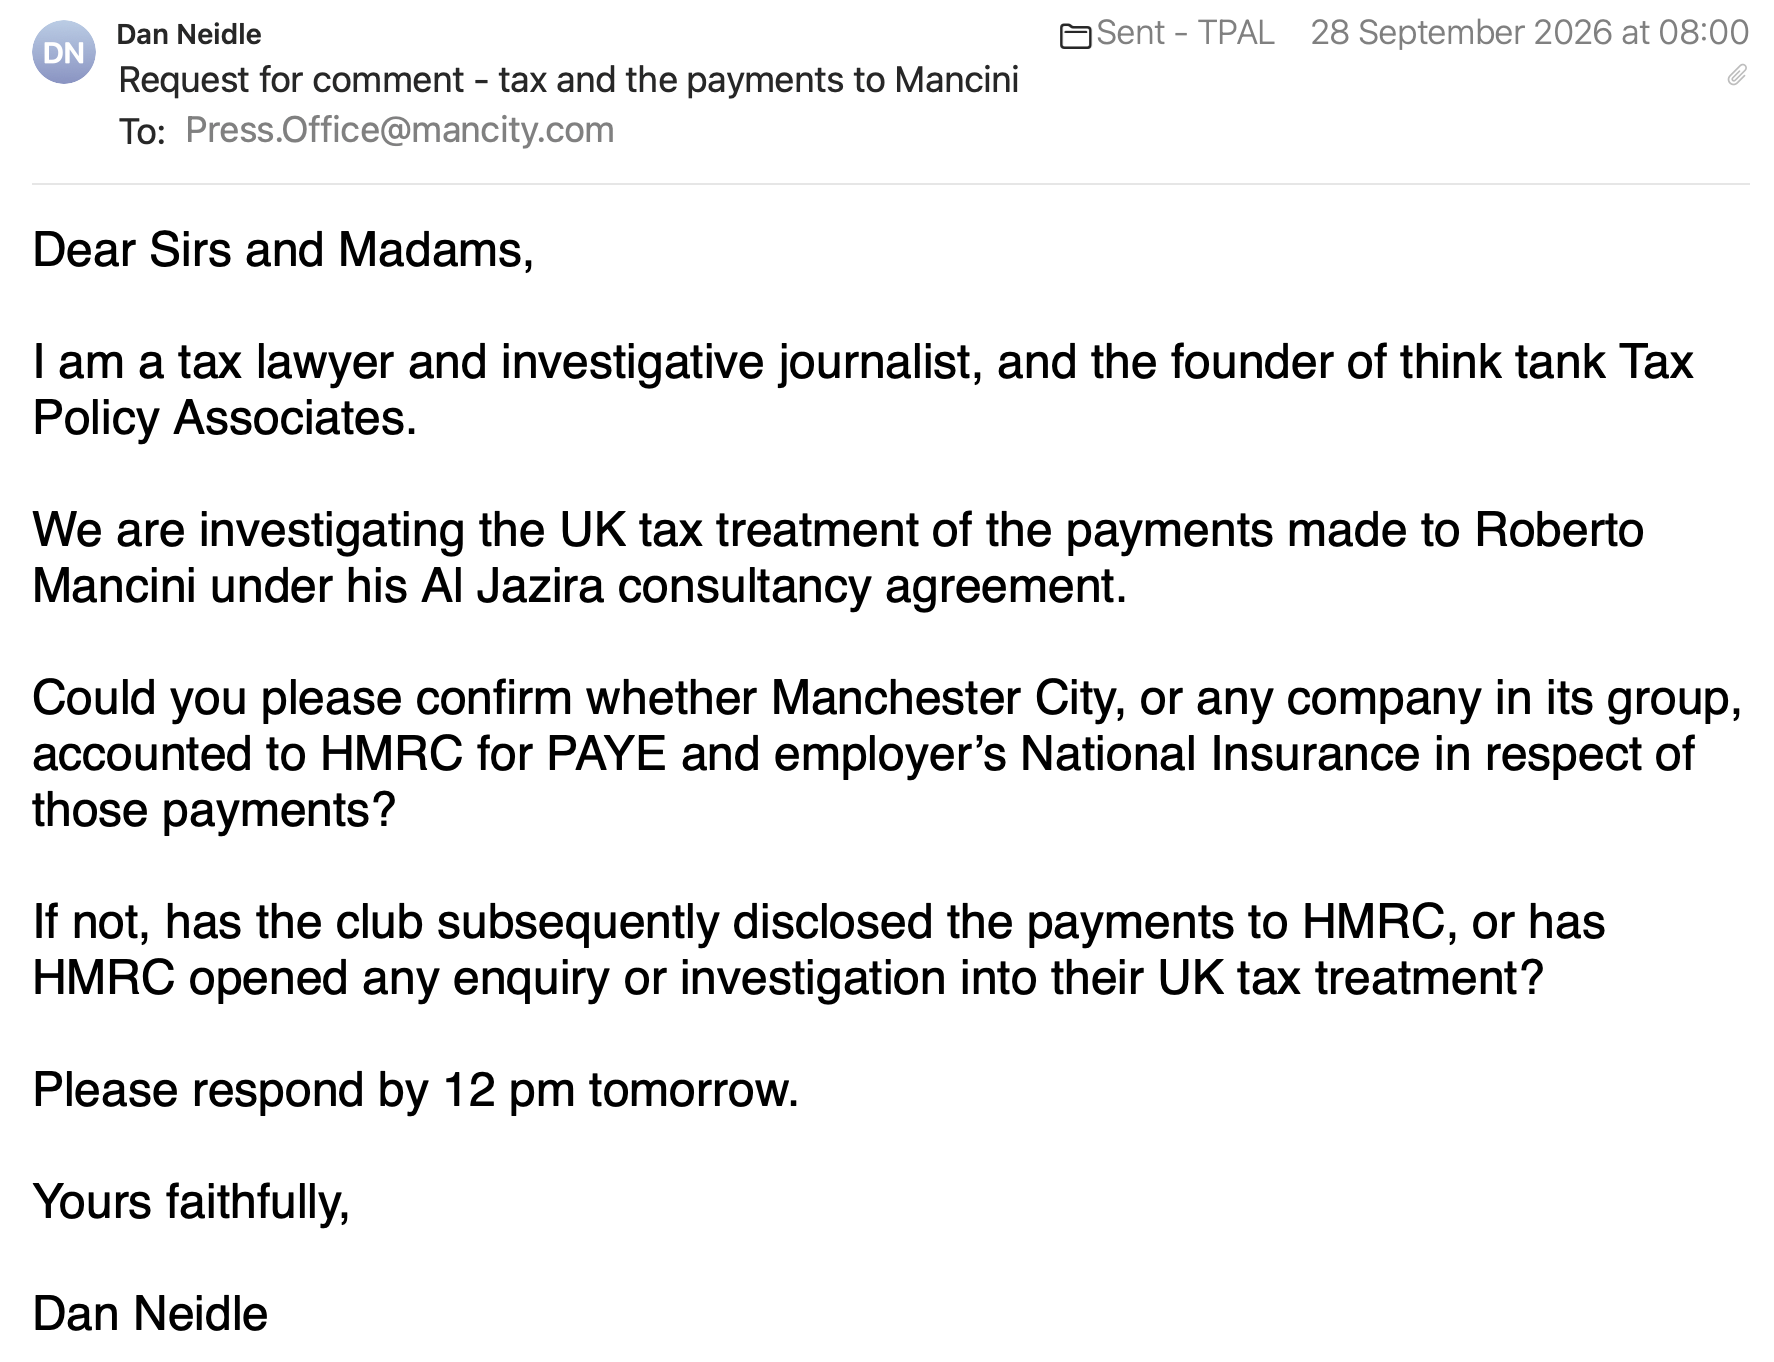
We didn’t receive a reply.
We sent a follow-up…
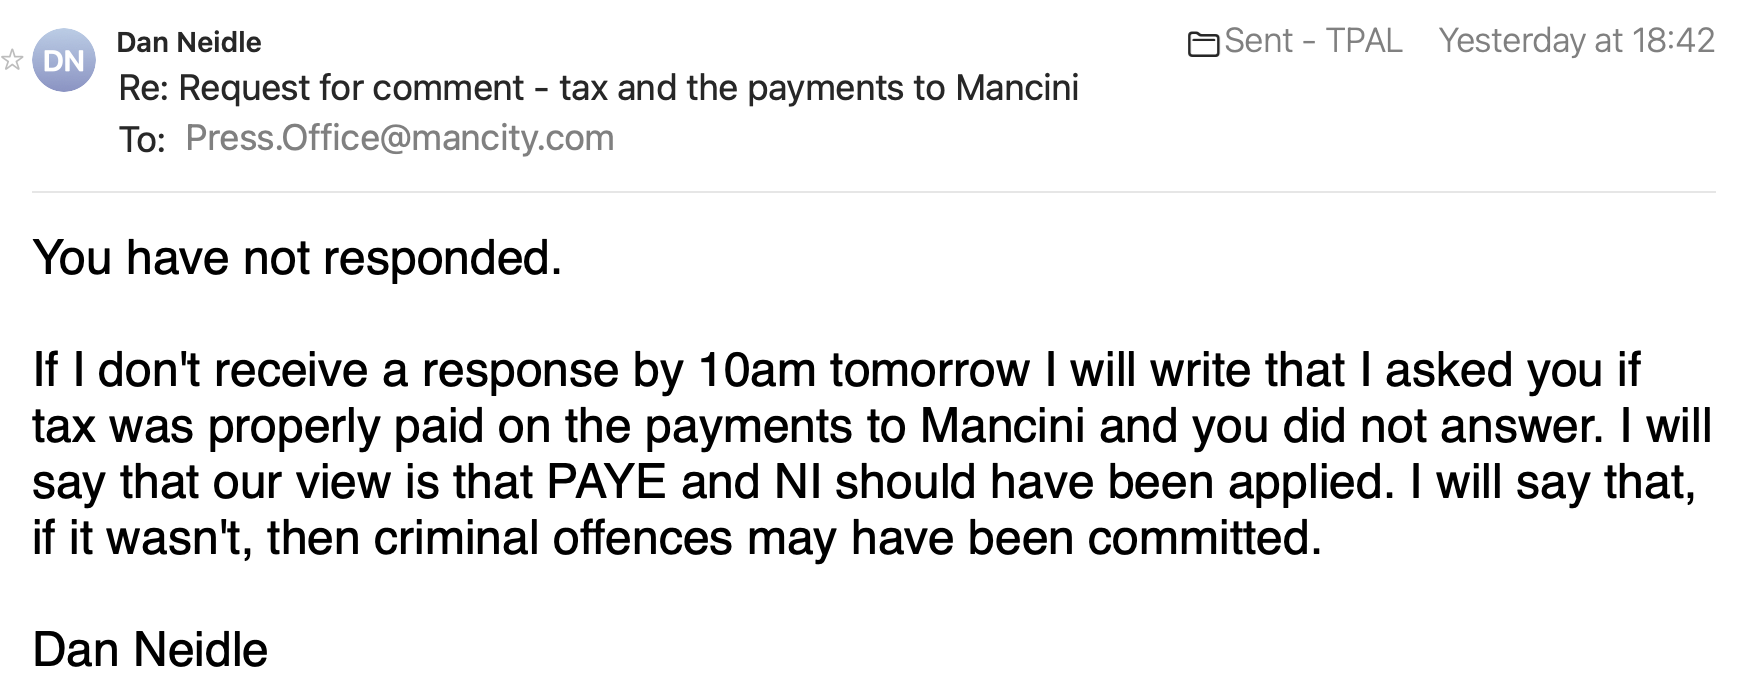
… and again received no reply. In our experience it is highly unusual for someone to not comment, or even respond, when we say we are going to accuse them of potentially committing a criminal offence.
The consequences
When Der Spiegel published in November 2018, HMRC said it would be “relentless in pursuing” any club that had tried to avoid tax and that it was visiting every Premier League club, while declining to comment on identifiable taxpayers. Nothing has been reported since. Manchester City’s accounts from 2018 to 2024/25 contain no quantified provision for tax on Mr Mancini’s contract, and the forensic accountants we work with haven’t been able to identify any sign of such a payment.
We would be surprised if HMRC hadn’t opened an enquiry at some point after 2018; it will have been well in time to do that.13
That enquiry could have been resolved in Manchester City’s favour (although that seems unlikely on the facts available to us). It could have ended with Manchester City paying the tax, but we see no sign of that in the club’s accounts.
So it is possible that the enquiry is ongoing, and eight years is not an unusual timeframe for a complex enquiry.
If the tax wasn’t paid at the time and it still hasn’t been paid today, but HMRC opened an enquiry within the time limits, then this is our estimate of the total amount that is due.14 It works out as considerably more than the figure would have been if City had simply complied with the law at the time – that’s an effect of paying people a “net of tax” amount:1516
| Tax on £8.87m paid to Mr Mancini | |
|---|---|
| Income tax and NIC | £11.6m |
| Interest to date | £7.0m |
| Penalty at 35% to 50% | £4.1m to £5.8m |
| Total | £23m to £24m |
One might think this is an unfair result because the club has already paid the Italian tax17, and now UK tax is being paid too. The flippant answer is that you should expect unfair results when you play these sorts of games. The technical answer is that if the position had been rectified earlier, then Mr Mancini could, in principle, have recovered some of the Italian tax, but it is now too late.18
In principle, Mr Mancini himself would be liable, but in most cases HMRC looks to recover the tax from the employer.
Was this tax evasion?
Unpaid tax and tax evasion are not the same thing.
Tax evasion involves a deliberate and dishonest attempt to evade tax, not merely an error or an unsuccessful legal argument. It’s most commonly prosecuted as the common-law offence of cheating the public revenue, but there are specific statutory offences as well.19
Let’s assume, as seems likely, that Manchester City should have applied PAYE and National Insurance to Mr Mancini’s consultancy payments, but didn’t. Why didn’t it? And does this rise to the level of a criminal offence?
The crucial legal question to determine whether a tax evasion offence was committed is whether the relevant personnel at City were “dishonest”.20 Under English law, this means asking whether their conduct was dishonest by the standards of ordinary decent people (regardless of whether the individuals themselves believed at the time that they were being dishonest).21
The usual defence people raise to a tax evasion prosecution is that they made a mistake, or they honestly thought what they were doing was correct.
The failure to deduct any UK tax from the consultancy agreement payments doesn’t look like a simple mistake; it seems to have been anticipated from the start. After all, the agreement said the fees “will be paid without deduction of any taxation”.
But the relevant City personnel might say that they believed the Al Jazira consultancy was a real and separate arrangement, genuinely referable to activity in Abu Dhabi, so that no UK tax was due. Yes, they got the tax wrong, and City owes the tax, interest and penalties, but they acted in good faith.
A defence like that is, however, hard to square with the leaked documents. City’s chief executive described the consultancy fee as part of Mr Mancini’s “guaranteed compensation”. City’s head of finance authorised the first payments out of City’s own bank account. After that, City’s finance team routinely sent the money to ADUG, for ADUG to send to Al Jazira, for Al Jazira to pay Mr Mancini’s company. And the Commission has found that the agreements were a sham (albeit to the civil and not criminal standard; and the Commission was not a jury).
Alternatively, they could accept that the consultancy agreement was a sham, designed to fool the Premier League, but say they had no idea that tax was due. Here it would be relevant to ask whether they obtained outside advice. If they did, and they followed that advice, then any prosecution would be challenging. If there was no tax advice on an arrangement this unusual then that raises its own questions.
Ultimately, whether to believe such a defence, and whether to find that the individuals were dishonest, would be for a jury to decide in light of all the facts: the tax reporting, the underlying communications and other evidence of the relevant individuals’ knowledge and intentions.
We should add that we are not suggesting that any specific individuals at Manchester City, or indeed Mr Mancini, committed an offence. We do not know. We are saying that there appear to be good grounds for a criminal investigation of the circumstances under which a sham arrangement was put in place and tax was not paid when it should have been.22
Are there other criminal offences?
This report focuses on Mr Mancini’s consultancy arrangement, but the facts set out in the decision suggest that the police should be looking at whether non-tax offences were committed.
False accounting
Section 17 of the Theft Act 1968 makes it an offence dishonestly to falsify accounting documents, with a view to gain for oneself or another, or an intention to cause loss to another.
The Commission found the accounts materially misstated income and expenses: paragraph 101. It found intentional concealment (paragraph 109) and that City knew the accounts did not give a true and fair view, or alternatively was reckless about that (paragraph 114).
Again, the crucial legal question to determine whether an offence was committed is whether the relevant personnel at City were “dishonest” (see the discussion above).
However, there is an additional challenge for a false accounting prosecution: did Manchester City’s personnel act with a “view to gain”? Manchester City may have ultimately been looking to make a gain from its cheating, but in the short term, its actions lost money rather than made it.23
Approving accounts which do not comply with the law
Section 393 of the Companies Act 2006 requires directors to be satisfied that accounts give a true and fair view before approving them. Under section 414(4), a director can commit an offence where non-compliant accounts are approved, the director knew of or was reckless about the non-compliance, and failed to take reasonable steps to secure compliance or prevent approval.
There’s also a specific company law offence that could apply: the accounts were then filed with Companies House, and it’s an offence to knowingly or recklessly deliver materially misleading, false or deceptive documents to Companies House.
The Commission found that nine seasons’ financial statements failed to give a true and fair view (paragraph 101) and that this was intentional (paragraph 114). That was, of course, to the civil rather than criminal standard, but on the face of it, there seems a strong case that a prosecution should be considered.
Misleading the auditors
Under section 501(1) of the Companies Act, knowingly or recklessly giving an auditor a materially misleading, false or deceptive statement can be an offence where it concerns information or explanations the auditor required, or was entitled to require.
The Commission says that even City’s auditors remained unaware of the disguised funding scheme (see footnote 7 to paragraph 68). It also describes documents generated to conceal the true arrangements from regulators and auditors (see paragraph 78).
Again, there seems a strong case for a criminal investigation here, subject again to the point that the decision was to the civil and not the criminal standard.
We are, once more, not saying that any particular individuals committed an offence. We do not know. We are saying there appear to be strong grounds for a criminal investigation.
Many thanks to M, K and P for their remuneration tax analysis, A, S and O for additional comments, and thanks to L for criminal law advice.
Thanks most of all to Der Spiegel and L’Espresso for their original 2018 reporting.
Disclosure: Manchester City is being represented by law firm Clifford Chance LLP. Our founder, Dan Neidle, was a senior partner at Clifford Chance until 2022. When he was a partner, he had no involvement in or knowledge of the case, and has at no time spoken to anyone at the firm regarding it.
Photo by Mylo Kaye on Unsplash.
The bizarre UK group selling US tax fraud to hundreds of Britons – and prosecuting its critics
Tax barristers and fraud: how the Bar responded to our allegations
Rogue barristers are enabling a billion pound tax fraud – and the Bar won’t act
New report: how Premier League Football clubs have avoided £470m of tax, and how to stop it
A £2.6bn lobbyist fairytale: economic consultancy Cebr sold VAT-free shopping as a tax cut that pays for itself
What effect is the mansion tax having on house prices?
Footnotes
City said the documents were “out-of-context materials purportedly hacked or stolen from City Football Group and Manchester City personnel and associated people”. That is not a denial of authenticity. We will leave the reader to decide whether and how the documents discussed below could be “out-of-context”. ↩︎
The argument goes: Cit’s accounts show that the “sponsorship income” (which wasn’t really sponsorship income) was treated as taxable income when it was really equity from its shareholder, which (one might think) is not taxable. So City declared too much income and overpaid tax. That is, however, likely not correct, because whilst a normal subscription for shares by a shareholder is indeed not taxable for a company, an injection of equity without receiving shares can be taxable. On the facts here, we think the payments likely were taxable (i.e., because the cash was necessary to support the business, and it went through the company’s profit and loss account). That implies that City paid the correct amount of corporation tax (although it is possible that were some ancillary expenses which were claimed as deductible but should not have been). Presumably the company did not structure the arrangement to treat the receipts as non-taxable because that would have revealed what it was up to; it also may not have care too much about artificially increasing its taxable income because, at the time, it was heavily loss-making. ↩︎
On the face of it, VAT wasn’t overpaid either, as the sponsors were outside the UK and Manchester City’s supplies to the sponsors (had they been real) wouldn’t have been subject to VAT. It is possible the deception caused VAT to be underpaid if (and we don’t know) Manchester City makes some exempt supplies and so does not recover all of its VAT. The deception might then have wrongly increased Manchester City’s VAT recovery. A simple example: suppose City incurs £100m of residual VAT supporting all its commercial activities. If its partial-exemption method allocates a material portion of that residual VAT to £800m of overseas sponsorship activity carrying a right to deduct, and £700m of the supposed sponsorship was really shareholder funding rather than consideration for any supply, the allocation methodology may have given City more recovery than its genuine economic activities justified. But without information as to City’s partial exemption method (if it has one) this is pure speculation. ↩︎
The code that made these measurements is on our GitHub. It gives the same result for the other places where the name is redacted. The box before “employment contract” is 49.0 points wide, and “Mancini’s” is 48.7 points. The box in the bold heading above paragraph 116 is 42.7 points wide, and “Mancini” in bold is 42.7 points. A matching width doesn’t identify anyone on its own: any name of the same width would fit, but given our conclusion that the individual concerned must have been a manager, there are only four possibilities. ↩︎
We are hosting these and some other documents on our website to reduce the risk they are taken down; copyright rests with the various authors, and we reproduce them in the public interest. ↩︎
From the bundle: signing-on fee £62,328.77, pro-rata fee £867,808.22, two quarters £875,000, one quarter £437,500, Italian gross-up £1,842,312, six grossed-up quarters £4,781,418. ↩︎
We have redacted the name of the presumably junior member of staff who inputted the payment. ↩︎
See Shilton v Wilmshurst [1991] 1 AC 684. Peter Shilton’s former club, Nottingham Forest, paid him £75,000 on condition that he agreed to be transferred to Southampton, because Forest needed Mr Shilton’s agreement in order to collect the £325,000 transfer fee from Southampton. The House of Lords held that the £75,000 was an emolument from Mr Shilton’s new Southampton employment. And, more recently, RFC 2012 Plc (in liquidation) v Advocate General for Scotland [2017] UKSC 45. Lord Hodge at paragraph 41: “As a general rule, therefore, the charge to tax on employment income extends to money that the employee is entitled to have paid as his or her remuneration whether it is paid to the employee or a third party.” People have played all kinds of games involving third parties; these are generally closed off by the disguised remuneration rules introduced in 2011. ↩︎
It’s very possible that Mr Mancini was a “non-dom”, and claimed the remittance basis, so that his foreign income was only taxed in the UK if he brought it here. That wouldn’t have helped. The remittance basis only applied to earnings from an employment with a foreign employer, where the duties were performed wholly outside the UK. These payments were earnings from Mr Mancini’s UK employment with Manchester City, for work done in the UK. They were fully taxable in the UK, wherever and however they were paid. The structure may have been designed to look like a structure that used to work. A non-domiciled individual with a UK employment and a genuinely separate employment with a foreign employer, for duties performed wholly abroad, paid abroad, was taxable on the foreign earnings only if he brought them to the UK. But this was closed for associated employers with related employments by section 24A ITEPA from 6 April 2014. In this case the number of days and the payment arrangements demonstrate there was no genuinely separate employment. ↩︎
This would have been straightforward for the payment made directly to him and more complex for the payment made indirectly, but the result would have been the same. Payments made by an intermediary on the employer’s behalf are treated as made by the employer. And, from 6 April 2011, the disguised remuneration rules require the employer to operate PAYE when a third party pays an employee’s reward to a person chosen by the employee. Those rules have an exception where the payer is in the same group as the employer, but the exception doesn’t apply where there’s a connection with a tax avoidance arrangement. ↩︎
There’s a suggestion the original intention was that the Mauritian company meant that no Italian tax would be due, and that at some point Mr Mancini or his advisers changed their mind. This was all around the time that the Italian tax authorities were pursuing high profile cases involving Italian individuals and companies using offshore companies to try to escape tax. ↩︎
If City had put the £1.75m through its UK payroll in 2011/12, it would have had to pay income tax at 50%, employee National Insurance at 2% and employer National Insurance at 13.8%. Under the consultancy arrangement, City covered Italian tax at 45.1%, and no National Insurance at all:
Annual cost of paying Mr Mancini £1.75m net UK payroll Italian consultancy Mr Mancini receives £1.75m £1.75m Income tax £1.82m £1.44m Employee National Insurance £0.07m nil Employer National Insurance £0.50m nil Total cost to City £4.15m £3.19m So the consultancy saved City almost £1m a year. Most of that saving is National Insurance, not the difference in income tax rates. ↩︎
For an employer, the equivalent of a discovery assessment is a “determination” under regulation 80 of the PAYE Regulations, which is subject to the same time limits as an assessment. Where a loss of tax is brought about deliberately, HMRC has twenty years, so 2010/11 stays open until 2031. City may well run a Tooth argument: it intended to deceive UEFA and the Premier League, not HMRC; if successful, then some years may be time-barred (2010/11 and 2011/12 were already closed before Der Spiegel published in November 2018). NIC is different: unpaid contributions are recovered as a debt subject to the six-year limit in the Limitation Act 1980, starting from the time HMRC discovered or could reasonably have discovered the concealment. So probably that took the deadline to November 2024. ↩︎
Income tax at 50%; employer NIC at 12.8% for 2010/11 and 13.8% thereafter; employee NIC at 1% then 2% above the upper earnings limit. ↩︎
The payments were made free of tax, so we treat the cash as a net amount and divide it by 0.5 to find the gross. We expect that would be HMRC’s approach here when the contract amount is stated to be net of tax. We have not grossed up for employee NIC, which would add a little more. If HMRC instead treated the cash paid as the gross amount, all the figures in the table would be roughly halved. ↩︎
Interest is simple interest at HMRC’s published rates. Penalties for a deliberate and concealed inaccuracy, prompted by HMRC, run from 50% to 100% of the tax; for deliberate but not concealed, 35% to 70%. The penalty is a percentage of the “potential lost revenue”, which here is the tax and NIC. We are being conservative here. The Commission’s findings of sham and of “intent to circumvent” are the language of the deliberate and concealed band, but HMRC settlements routinely land at the bottom of the range when there is reasonable cooperation. ↩︎
Or, to be precise, Mr Mancini paid, and Manchester City covered the cost. ↩︎
The domestic Italian four-year window closed in 2017, the treaty’s mutual agreement procedure is discretionary and Italy has historically declined to override its own time limits. The exchange of notes attached to the treaty confirms that domestic time limits still have to be observed. ↩︎
For example, being concerned in the fraudulent evasion of income tax under section 106A of the Taxes Management Act 1970. There’s an equivalent offence of fraudulently evading National Insurance contributions. ↩︎
A company can only commit these offences if responsibility lies with its directors (its “directing mind and will”); that is unusual (or, to be more precise, being able to prove it is unusually difficult). The corporate offence of failing to prevent the facilitation of tax evasion only applies to conduct from 30 September 2017, long after these payments. ↩︎
The subjective element of the test for dishonesty (see Ghosh (1982)) was removed by Ivey [2017] for civil cases, and that decision was confirmed to apply to criminal cases in Barton [2020]. The fact that a defendant might plead he or she was acting in line with what others were doing, and therefore did not believe it to be dishonest, is no longer relevant if the jury finds they knew what they were doing and it was objectively dishonest. The leading textbook of criminal law and practice, Archbold, states: “In most cases the jury will need no further direction than the short two-limb test in Barton “(a) what was the defendant’s actual state of knowledge or belief as to the facts and (b) was his conduct dishonest by the standards of ordinary decent people?””. ↩︎
HMRC’s stated policy is “to deal with fraud by use of the cost effective civil fraud investigation procedures under Code of Practice 9 wherever appropriate”, with criminal investigation reserved for cases where HMRC “needs to send a strong deterrent message or where the conduct involved is such that only a criminal sanction is appropriate”. The circumstances HMRC lists include the use of false documents. It would almost certainly be more cost effective to collect the tax and penalties and not prosecute. But if the facts support a prosecution then in our view that would be a mistake. ↩︎
“Gain” is defined as a gain in money or other property, whether temporary or permanent, and includes keeping what one has. ↩︎
Leave a Reply